The NCP blog
Will Insurance Cover Your Miami Floor Coating Project Gone Wrong
Polished concrete9 min read
Licensed Florida contractors are required by statute to carry general liability insurance with minimum coverage of $300,000.
The short answer: it depends on what went wrong and who caused it. Floor coating project insurance claims in Miami fall into three categories: contractor liability coverage (when the installer made errors), homeowner’s insurance (when covered perils like water damage destroy your floor), and manufacturer warranties (when products fail despite proper installation). Understanding which applies to your situation can mean the difference between a full repair and paying thousands out of pocket.
According to the Insurance Information Institute, flooring claims represent approximately 12% of all interior home improvement disputes filed with insurance carriers annually. In South Florida, that percentage rises to nearly 18% due to our unique climate challenges with humidity and moisture-related failures.
Understanding Insurance Coverage Types for Floor Coating Projects
Before filing any claim, identify which coverage applies to your situation. Each type has different requirements, limitations, and processes.
Contractor Liability Insurance
Licensed Florida contractors are required by statute to carry general liability insurance with minimum coverage of $300,000. This coverage protects homeowners when installation errors cause damage. Common covered scenarios include:
Improper surface preparation leading to coating delamination. Failure to perform adequate moisture testing resulting in bubbling or peeling. Application errors causing uneven coverage, fisheyes, or premature wear. Damage to adjacent property during installation.
The Florida Department of Business and Professional Regulation reports that 23% of contractor complaints involve flooring installations, with epoxy peeling being the most common issue cited.
Homeowner’s Insurance Coverage
Standard HO-3 policies in Florida typically cover floor damage from named perils only. These include fire, lightning, windstorm, hail, explosion, smoke, vandalism, and certain water damage events. Coverage does not extend to:
Workmanship defects or installation failures. Normal wear and tear. Gradual moisture damage from concrete moisture vapor transmission. Flooding (requires separate flood insurance). Settling, cracking, or structural movement.
Key distinction: If a covered peril like a burst pipe damages your existing floor coating, your homeowner’s policy may cover replacement. If the coating simply failed due to poor installation or product defects, homeowner’s insurance will deny the claim.
Manufacturer Product Warranties
Quality epoxy and polyaspartic coating manufacturers offer warranties ranging from 5 to 25 years. These warranties cover product defects such as premature yellowing (in UV-stable formulations), chemical breakdown not caused by misuse, and adhesion failure when applied according to specifications.
However, manufacturer warranties contain strict conditions. Most require documentation that the product was applied within specified temperature and humidity ranges, that proper surface profile was achieved, and that application thickness met specifications.
Floor Coating Insurance Coverage Comparison
| Issue Type | Contractor Liability | Homeowner’s Policy | Manufacturer Warranty |
|---|---|---|---|
| Installation errors | Covered | Not Covered | Not Covered |
| Product defects | Not Covered | Not Covered | Covered |
| Water damage (burst pipe) | Not Covered | Covered | Not Covered |
| Moisture vapor damage | Possibly Covered* | Not Covered | Not Covered |
| Hurricane damage | Not Covered | Covered | Not Covered |
| Premature yellowing | Not Covered | Not Covered | Possibly Covered* |
| Hot tire pickup | Possibly Covered* | Not Covered | Possibly Covered* |
*Coverage depends on specific policy terms, documentation of proper installation, and root cause determination.
Documentation Requirements for Successful Claims
Insurance claims live or die based on documentation. The National Association of Insurance Commissioners reports that 34% of denied home improvement claims result from insufficient documentation rather than coverage exclusions.
Before Installation Documentation
Photograph the existing floor condition from multiple angles. Record moisture test results with date stamps. Obtain copies of the contractor’s license, insurance certificate, and bond information. Keep the signed contract specifying materials, methods, and warranty terms.
Request product data sheets for all materials used. Professional installers should provide documentation of concrete surface profile achieved during preparation, ambient temperature and humidity readings during application, and coating thickness measurements.
During Installation Documentation
Take timestamped photos at each stage of the installation process. Record any deviations from the original scope of work. Note weather conditions, particularly if work occurs during Miami’s rainy season when humidity can affect curing.
After Installation Documentation
Keep detailed records of maintenance activities and products used. Document any changes in appearance or performance with dated photographs. Save all communication with the contractor regarding warranty service requests.
Common Floor Coating Claim Scenarios in Miami
Scenario 1: Coating Delamination Within the First Year
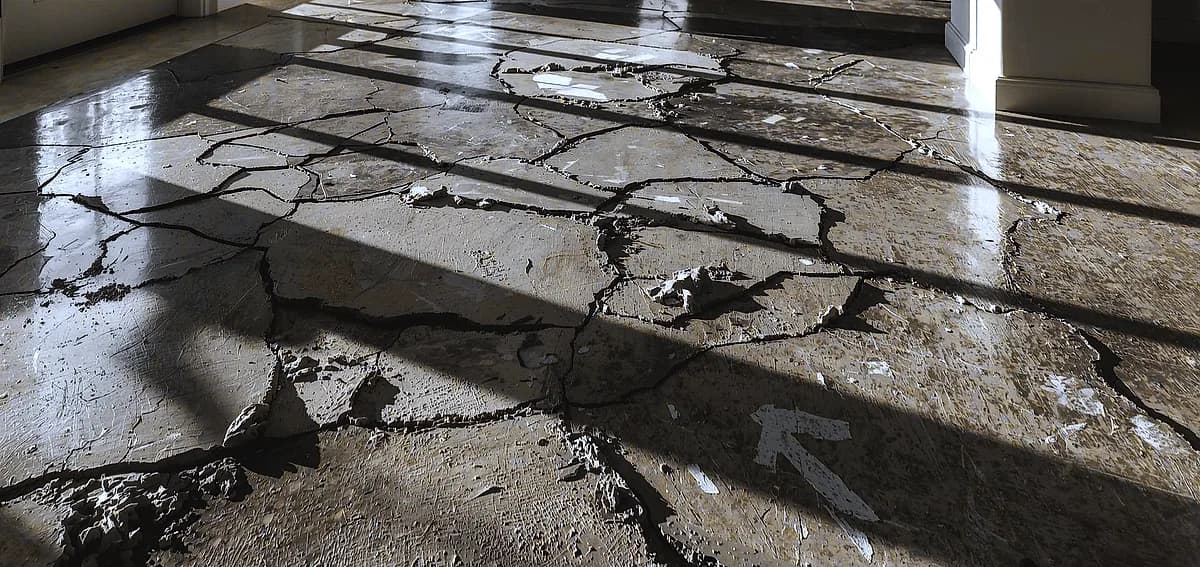
Delamination, where the coating separates from the concrete substrate, is the most common failure in South Florida. The root cause determines coverage eligibility.
If caused by inadequate surface preparation: Contractor liability insurance applies. Florida Building Code requires contractors to achieve proper concrete surface profile (CSP 2-3 for most coatings) and verify moisture levels below 4 lbs/1000 sq ft/24 hours.
If caused by undetected moisture vapor transmission: Coverage depends on whether proper moisture testing protocols were followed. If the contractor performed standard tests and results were acceptable, the failure may fall outside coverage.
Scenario 2: Hot Tire Pickup in Garage Coatings
Hot tire pickup occurs when warm tires from a recently driven vehicle soften and lift the coating. In Miami’s climate, where asphalt temperatures can exceed 150°F in summer, this issue affects improperly specified coatings.
Likely covered by contractor liability: If the contractor specified materials not rated for high-temperature resistance. Professional-grade garage floor coatings and polyaspartic systems are designed to resist temperatures up to 300°F.
May be covered by manufacturer warranty: If documentation shows proper installation but the product failed to meet its stated temperature resistance specifications.
Scenario 3: Hurricane-Related Floor Damage
Hurricane damage to floor coatings typically involves flood water intrusion, debris impact, or prolonged exposure to standing water. Homeowner’s insurance coverage varies significantly.
Wind damage: Generally covered under standard policies if wind-driven rain enters through damaged windows or roofing and damages your polished concrete or coated floors.
Flood damage: Requires separate NFIP flood insurance. Standard homeowner’s policies explicitly exclude flood damage. In Miami-Dade and Broward counties, FEMA reports that 67% of homes lack adequate flood coverage.
Steps to Filing a Successful Floor Coating Claim
Step 1: Identify the Root Cause
Before contacting any insurance carrier, determine what caused the failure. Consider hiring an independent flooring inspector certified by ICRI (International Concrete Repair Institute). Inspection costs typically range from $300 to $600 but can prevent thousands in misdirected claims.
Step 2: Contact the Appropriate Party
For installation defects, contact your contractor first. Florida law requires contractors to attempt repairs before homeowners can pursue insurance claims. Document all communication in writing. If the contractor is unresponsive or disputes responsibility, file a complaint with the Florida Department of Business and Professional Regulation.
For covered perils (fire, water damage, wind), file a claim with your homeowner’s insurance carrier within 3 years (Florida’s statute of limitations for property claims). For manufacturer defects, contact the product manufacturer directly with your installation documentation.
Step 3: Document Everything
Photograph damage extensively from multiple angles and distances. Create a written timeline of when the problem first appeared and how it progressed. Gather all original installation documentation including contracts, invoices, product data sheets, and photos. Obtain written repair estimates from at least two licensed contractors.
Step 4: Understand Depreciation and Limits
Insurance payouts account for depreciation. A 10-year-old epoxy floor with a 15-year expected lifespan will only be covered at 33% of replacement value in many policies. Understand your policy’s coverage limits and deductibles before filing.
Preventing Claims Through Quality Installation
The best insurance claim is one you never have to file. Working with qualified contractors who follow industry standards dramatically reduces failure risk.
Contractor Selection Criteria
Verify active Florida contractor licensing through the DBPR website. Confirm current general liability insurance with coverage of at least $1 million. Request references specifically from Miami-area installations completed more than two years ago. Ensure the contractor uses professional-grade materials from reputable manufacturers.
Pre-Installation Requirements
Insist on comprehensive moisture testing using calcium chloride or relative humidity probe methods. Require documentation of surface preparation methods and achieved profile. Ensure environmental conditions (temperature 50-90°F, relative humidity below 85%) are documented during application.
Warranty Considerations
Understand the difference between contractor warranties and manufacturer warranties. A contractor warranty covers workmanship for typically 1-5 years. A manufacturer warranty covers product performance but often requires installation by a certified applicator to remain valid.
Miami-Specific Insurance Considerations
South Florida’s insurance market presents unique challenges. Citizens Property Insurance Corporation data shows that flooring claims in Miami-Dade County average 23% higher than the national average due to climate-related damage.
Humidity and Moisture Exclusions
Most policies exclude damage from gradual moisture infiltration, which is particularly relevant for concrete moisture issues common in South Florida. If moisture vapor transmission causes coating failure over months or years, neither homeowner’s insurance nor contractor liability will typically cover the damage.
Prevention through proper moisture barriers and vapor mitigation systems is essential. These add $2-4 per square foot to installation costs but prevent far more expensive failures.
Hurricane Deductibles
Florida hurricane deductibles are percentage-based, typically 2-5% of the dwelling coverage amount. For a home insured at $500,000, a 2% hurricane deductible equals $10,000 out of pocket before coverage begins. Minor floor damage from hurricane-related water intrusion may not meet this threshold.
When to Consult an Attorney
Legal consultation becomes necessary in several situations. If the contractor’s insurance carrier denies your claim without adequate explanation. If your homeowner’s insurance denies a claim you believe should be covered. If the contractor has abandoned the project or gone out of business. If damages exceed $15,000 (the threshold for Florida small claims court).
Florida has strong contractor licensing laws. Operating without a proper license is a felony, and contracts with unlicensed contractors may be voidable, potentially leaving you with limited recourse.
Frequently Asked Questions
Does homeowner’s insurance cover epoxy floor replacement?
Only if damage results from a covered peril such as fire, burst pipes, or wind damage. Normal wear, installation defects, and gradual moisture damage are excluded from standard HO-3 policies. Document the cause of damage thoroughly before filing any claim.
How long do I have to file a floor coating insurance claim in Florida?
Florida’s statute of limitations for property insurance claims is 3 years from the date of loss. For contractor liability claims, you have 4 years for breach of contract or 2 years for negligence claims. Report damage to your insurer as soon as it’s discovered to avoid coverage disputes.
What if my contractor doesn’t have insurance?
Licensed Florida contractors must carry liability insurance. If yours doesn’t, they may be operating illegally. You can file a complaint with the DBPR and potentially recover damages through the Construction Industry Recovery Fund, which provides up to $50,000 per claimant for losses caused by licensed contractors.
Will my claim increase my insurance premiums?
Filing a claim may impact future premiums, though the effect varies by insurer and claim type. In Florida’s volatile insurance market, a single claim can result in premium increases of 10-25% or even non-renewal. Consider whether the claim amount exceeds your deductible plus potential premium increases over 3-5 years before filing.
Can I claim floor coating damage on my taxes?
Casualty losses from federally declared disasters may be tax-deductible. Standard installation failures or maintenance issues are not deductible. Consult a tax professional regarding specific circumstances, particularly if damage occurred during a declared hurricane or other federal disaster.
What documentation do insurance adjusters look for in floor coating claims?
Adjusters evaluate original installation contracts and invoices, proof of proper licensing and insurance for the installer, product specifications and data sheets, documentation of environmental conditions during installation, maintenance records, before and after photographs, and expert opinions on the cause of failure. Missing documentation significantly weakens claims.
Written by
Founder and CEO
Chris Lavin is an esteemed leader in concrete polishing and epoxy coatings with a distinguished 20-year career. As founder and CEO of National Concrete Polishing and owner of Xtreme Polishing Systems, he's renowned for polishing and epoxy coating more floors than anyone globally. Chris is recognized for his innovative approach and commitment to enhancing floor durability and aesthetics. His hands-on experience and technical proficiency make him a respected authority and a valuable resource in the field of floor polishing and coatings.
Same topic
Related articles
All stories
Polished concrete11 min read
Polished Concrete vs Epoxy Coatings: Which Floor Is Right for Your Space?
Two systems, two price curves, one slab. What each one costs to install and to keep, and which spaces each one actually suits.
Read it
Polished concrete8 min read
What to Know Before Polishing Your Existing Concrete Slab
Before any mechanical refinement can begin, a thorough evaluation of the current foundation is required.
Read it
Polished concrete8 min read
Is Polished Concrete Worth the Investment for Miami Properties?
It is essential to distinguish between a simple topical seal and mechanically refined concrete.
Read it
Tell us about the floor
Tell us the space and roughly how big it is.We come back with what it would cost and when we could start.
Prefer to talk? Call +1 844-876-5474
- Leads@
nationalconcretepolishing.net - 2200 NW 32nd St #600,
Pompano Beach, FL 33069 Mon to Fri, 9:00 to 5:30